Ocala and Marion County still feel like a place where you can find a yard and a reasonable commute. The mortgage process does not have to feel like a second job. Stress Less Mortgage, founded by Eric Eckenroth in Belleview, works purchase files for buyers who actually live here, not for a national lead mill.
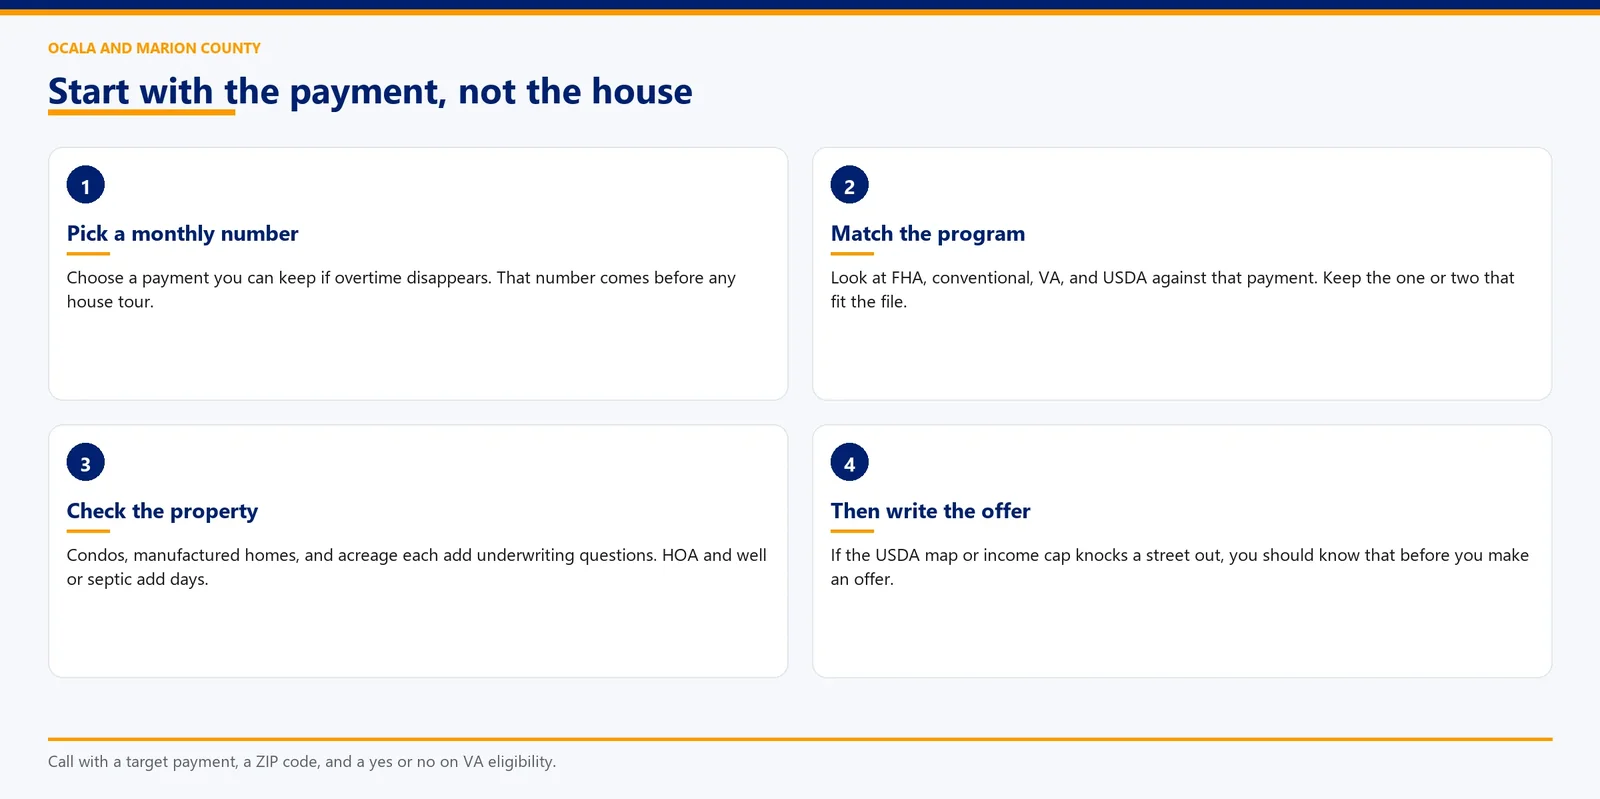
Start with the payment, not the house
Pick a monthly number you can keep if overtime disappears. Then look at FHA, conventional, VA, and USDA against that number. Each program has different down payment, credit, and property rules. The "best" loan is the one you can close and still afford in July when the electric bill jumps.
Our team will not stack four programs in one conversation to sound complete. We pick the one or two that match the file. If USDA income limits or the rural map knock a street out, you should know that before you write an offer.
Ocala, Belleview, and The Villages
Ocala proper, Belleview, and the edges toward The Villages do not share the same housing stock. Condos, manufactured homes, and acreage each carry extra underwriting questions. HOA documents and well or septic inspections add days. Build that into the contract calendar.
If you also work in Orlando, Tampa, or Jacksonville and want a house here, say so. The commute is your call to accept. The occupancy and income documentation is the loan's job, and those have to line up.
Self-employed and investors
Bank statement and DSCR options exist for small-business owners and investors when a W-2 file is the wrong shape. They are not a way to skip credit or reserves. Bring 12 months of statements or a rent schedule and expect follow-up questions.
Credit is not a personality score. A thin file and a bruised file need different programs. If you had a late payment during a medical year, say that. If you have almost no credit, say that too. We can tell you whether a few months of tradeline work is smarter than forcing a purchase this quarter.
Older Ocala stock brings roof age, HVAC, wells, and septic into the file. A cheap list price that needs twenty thousand in work is not a bargain if FHA or USDA cannot close on it. After you are pre-approved, keep the same job and skip large new purchases until closing. A car payment in week three of underwriting is how files die.
How to work with our team
Call with a target payment, a ZIP code, and a yes or no on VA eligibility. We can tell you if a full application is worth your time this month. As an independent brokerage, Stress Less Mortgage compares programs across multiple wholesale lenders, so the useful next step is a conversation, not a maze of forms.
Call (352) 572-9060, schedule a mortgage call, or start your application when you are ready.
This is not a commitment to lend. All loans are subject to credit approval and underwriting. Programs and terms can change. Stress Less Mortgage LLC, Company NMLS #1789928. Eric Eckenroth, NMLS #1263286. Equal Housing Lender.