The Villages is full of homeowners who bought right, stayed, and now wonder if a refinance is worth the closing costs. Sometimes it is. Sometimes it only looks good on a postcard rate. Our team at Stress Less Mortgage runs those numbers for people in The Villages, Ocala, and Belleview, including a VIP refinance path when the file fits.
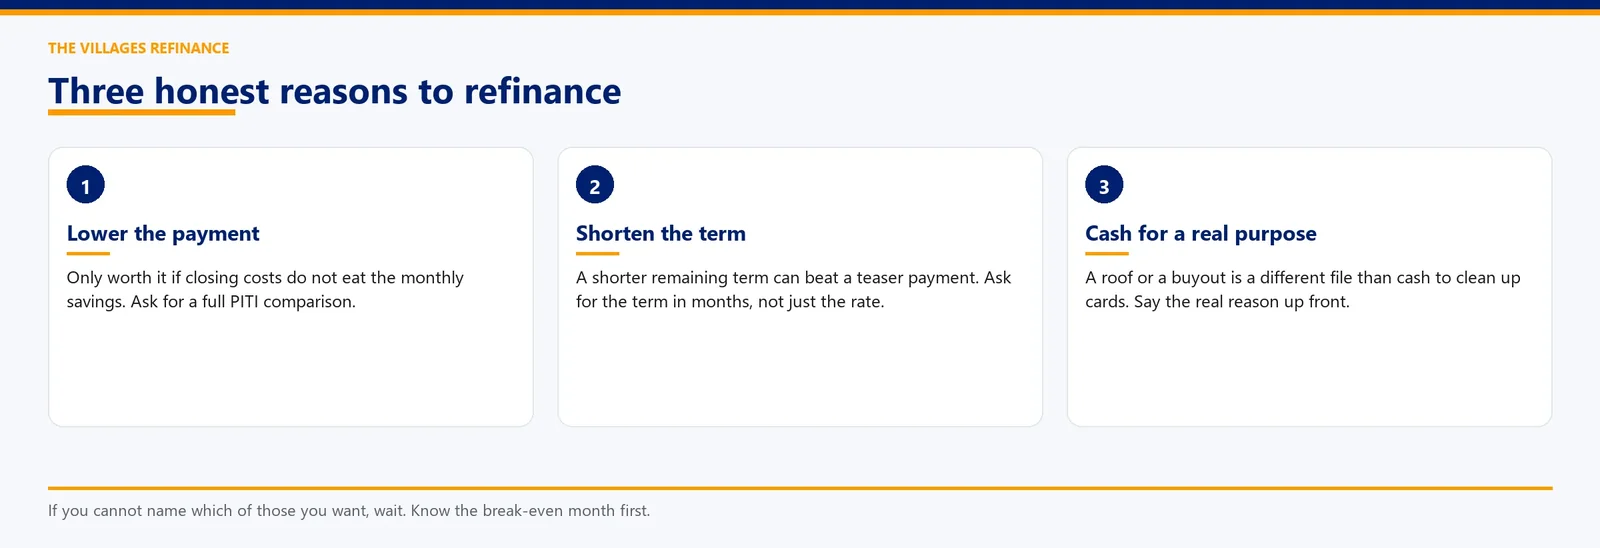
Three honest reasons to refinance
Lower the payment. Shorten the term. Pull cash for a documented purpose. If you cannot name which of those you want, wait. Refinancing to "see what happens" is how people spend two thousand dollars to save eleven dollars a month.
We put closing costs next to monthly savings and a break-even month. If you might move in two years, that month matters more than the headline rate. No post can quote your rate. Your credit, occupancy, and loan balance do.
VA, conventional, and cash-out
Veterans who used VA to buy can often refinance inside VA rules. Conventional cash-out has equity and credit tests. FHA streamlines exist for some FHA borrowers. The program has to match the current loan, not the one you wish you had started with.
Cash-out for a roof or a buyout is a different conversation than cash-out to clean up cards. Say the real reason. Underwriting will see it anyway. If consolidating debt is the goal, start with our debt consolidation refinance page.
What slows a Villages refinance
HOA questionnaires, appraisals on unique properties, and title issues on older homes add time. If you need the funds before a trip or a family event, start earlier than you think. We can keep the file moving. We cannot make an HOA manager answer email faster.
Break-even is not the only test. If you are close to paying off a short remaining term, a lower rate can still be a bad trade. Ask for the remaining term in months, not just the payment.
Taxes and insurance in The Villages can re-escrow after a refinance. The new payment is not only principal and interest. If the old escrow was thin, the monthly number can jump even when the rate drops. Ask for a full PITI comparison, not a principal and interest teaser.
If a prior refinance sat in processing for a month and died, bring that story. Duplicate credit pulls and stale appraisals waste time. We can start a fresh application, but we cannot resurrect a file that lived at another shop unless you have the documents.
Next step
A fifteen minute call is enough to know if a full application is worth it. Call (352) 572-9060, schedule a mortgage call, or run the refinance analysis first.
This is not a commitment to lend. All loans are subject to credit approval and underwriting. Programs and terms can change without notice. Stress Less Mortgage LLC, Company NMLS #1789928. Eric Eckenroth, NMLS #1263286. Equal Housing Lender.